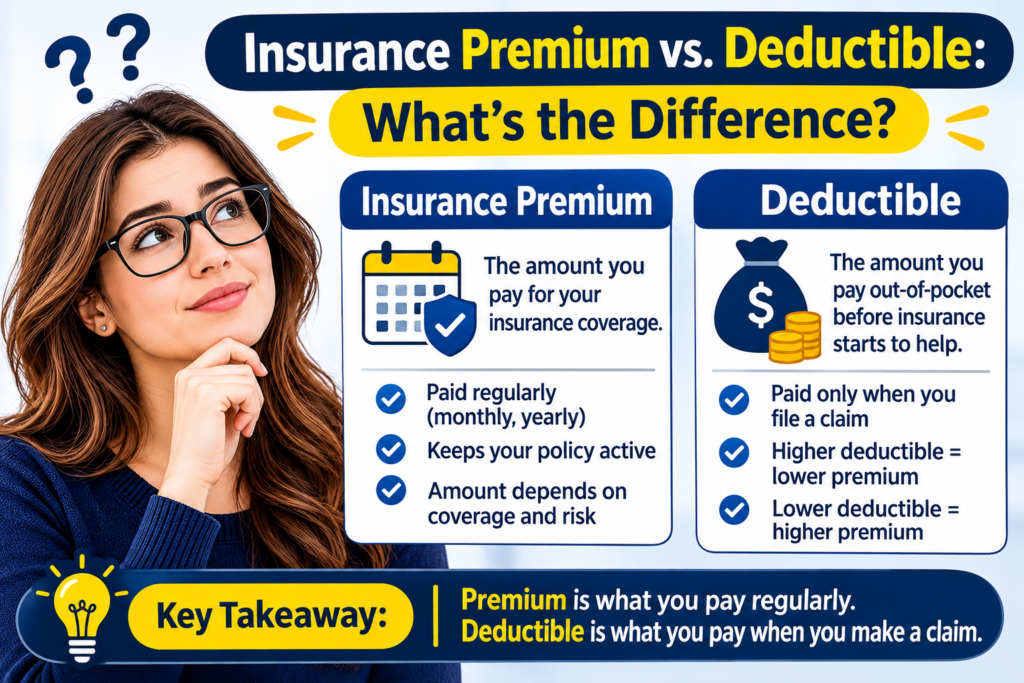

When buying insurance, you will often come across two important terms: premium and deductible. Both affect how much you pay for insurance, but they work in different ways.
Understanding the difference between an insurance premium and a deductible can help you choose a policy that fits your budget and financial situation.
For example, you might pay a monthly amount to keep your car insurance active. If you have an accident, you may also need to pay a certain amount before your insurance company covers eligible repair costs. These are two different insurance expenses.
In this guide, we will explain what an insurance premium and deductible mean, how they work, how they affect your insurance costs, and how to choose the right balance.
What Is an Insurance Premium?
Table of Contents
An insurance premium is the amount you pay to an insurance company to maintain your insurance coverage.
Depending on the policy, you may pay your premium monthly, quarterly, every six months, or annually.
For example, imagine your car insurance premium is $120 per month. You would pay $1,440 over 12 months if the rate remained unchanged.
Your premium is generally required whether or not you make an insurance claim.
What Affects Your Insurance Premium?
Insurance companies consider different factors when calculating premiums. These factors depend on the type of insurance you purchase.
For example:
- Age: Age may affect the price of certain insurance policies.
- Location: Where you live can influence insurance costs.
- Coverage amount: Higher coverage limits can increase premiums.
- Claims history: Previous insurance claims may affect your price.
- Risk factors: Insurers evaluate the risks associated with the policy.
- Deductible: Choosing a higher deductible can sometimes reduce your premium.
The exact factors and their importance vary by insurer and insurance type.
What Is an Insurance Deductible?
A deductible is the amount you must pay toward a covered claim before your insurance company pays its share, according to the policy terms.
For example, imagine your car insurance policy has a $500 deductible. After a covered accident, eligible repairs cost $3,000.
If the deductible applies, you pay the first $500, and the insurance company pays the remaining $2,500, assuming the claim is approved and there are no other applicable limits or exclusions.
Deductibles are common in several types of insurance, including:
- Car insurance
- Homeowners insurance
- Renters insurance
- Health insurance
- Certain business insurance policies
Not every insurance policy uses a deductible, and the rules can differ between policies.
Insurance Premium vs. Deductible: Key Differences
The biggest difference is when and why you pay each amount.
| Feature | Insurance Premium | Insurance Deductible |
|---|---|---|
| Meaning | Cost of maintaining coverage | Amount you pay toward an applicable claim |
| When you pay | Regularly or according to the payment schedule | When a covered claim requires it |
| Main purpose | Keeps your policy active | Shares claim costs between you and the insurer |
| Claim required? | No | Usually applies when making a relevant claim |
| Higher amount means | Higher regular insurance cost | More out-of-pocket cost for a covered claim |
| Effect on price | Directly determines policy cost | A higher deductible may lower the premium |
Example: How Premium and Deductible Work Together
Let’s understand both terms with a simple example.
Imagine you purchase a car insurance policy with these terms:
- Monthly premium: $120
- Annual premium: $1,440
- Deductible: $500
- Approved covered repair cost: $3,000
If you have an accident and the policy covers the damage, the calculation may look like this:
| Expense | Amount |
|---|---|
| Annual insurance premium | $1,440 |
| Covered repair cost | $3,000 |
| Your deductible | $500 |
| Insurer’s payment | $2,500 |
You pay the insurance premium to maintain coverage. If an applicable claim occurs, you also pay the deductible.
Remember that the premium is separate from the deductible. Paying your premium does not mean you have already paid your deductible.
Does a Higher Deductible Lower Your Premium?
In many insurance policies, choosing a higher deductible can reduce your premium.
This happens because you agree to pay more toward an eligible claim before the insurer contributes.
For example, an insurer might offer different deductible options:
| Deductible | Possible Premium Effect |
|---|---|
| $250 | Higher premium |
| $500 | Moderate premium |
| $1,000 | Lower premium |
These are illustrative comparisons, not actual insurance quotes. The available options and savings depend on the insurer and policy.
A higher deductible may save you money on regular payments, but you need to be prepared to pay more if you make a claim.
Should You Choose a High or Low Deductible?
There is no single deductible that is best for everyone. Your choice should depend on your savings, monthly budget, and ability to handle unexpected expenses.
Benefits of a High Deductible
A higher deductible may be suitable if:
- You have enough emergency savings.
- You want to reduce your regular premium.
- You can afford a larger payment after a covered claim.
- You are comfortable taking on more of the initial claim cost.
However, choosing a deductible that is too high can create financial problems after an unexpected accident or loss.
Benefits of a Low Deductible
A lower deductible may be suitable if:
- You have limited emergency savings.
- You prefer smaller out-of-pocket payments when making a claim.
- You want more predictable claim expenses.
- You can comfortably afford the higher premium.
The disadvantage is that you may pay more for insurance even if you never make a claim.
How to Choose the Right Balance
Before selecting an insurance policy, consider these practical steps.
1. Review your monthly budget
Calculate how much you can comfortably spend on insurance without affecting essential expenses.
2. Check your emergency savings
Think about how much you could afford to pay immediately if an accident or covered loss happened.
3. Compare different deductible options
Ask insurers for quotes with different deductibles. Compare the actual premium difference rather than assuming a higher deductible will always save a significant amount.
4. Read the policy details
Check whether different coverage sections have separate deductibles, special limits, or exclusions.
5. Consider your personal risk
Your driving habits, property, location, and financial circumstances may affect which option makes sense.
6. Compare the total cost
Do not look at the monthly premium alone. Consider the premium, deductible, coverage limits, exclusions, and other out-of-pocket expenses.
Premium vs. Deductible in Different Types of Insurance
The relationship between premiums and deductibles can vary depending on the insurance product.
Car Insurance
Car insurance premiums are generally paid monthly or according to the policy schedule. A deductible may apply to collision or comprehensive coverage, depending on the policy.
For example, if your covered vehicle damage costs $2,000 and your applicable deductible is $500, you may pay $500 while the insurer pays the remaining eligible $1,500.
Health Insurance
Health insurance premiums are payments made to maintain your health coverage.
A health insurance deductible is the amount you generally pay for covered services before your plan begins paying according to its cost-sharing rules.
However, some services may be covered before you meet the deductible, depending on your plan. Copayments, coinsurance, and out-of-pocket maximums are also important.
Homeowners Insurance
Homeowners insurance premiums maintain your home insurance policy.
If your home suffers covered damage, a deductible may apply before the insurer pays the eligible claim amount.
Some policies have different deductibles for specific types of damage, so read the policy carefully.
Renters Insurance
Renters insurance premiums are generally affordable compared with many other insurance products, although prices vary.
If your personal belongings are damaged or stolen in a covered event, your deductible may apply to the claim.
Common Mistakes to Avoid
When comparing insurance policies, avoid these common mistakes:
- Choosing a policy only because it has the lowest premium.
- Selecting a high deductible without enough emergency savings.
- Assuming every type of claim has the same deductible.
- Ignoring exclusions and coverage limits.
- Forgetting to compare the total cost of different policies.
- Assuming that paying a premium guarantees every claim will be approved.
Understanding these details can help you avoid unexpected expenses.
Frequently Asked Questions
Is an insurance premium the same as a deductible?
No. A premium is the amount you pay to maintain your insurance coverage. A deductible is the amount you pay toward an applicable covered claim before the insurer pays its share.
Do I pay a deductible every month?
No. A deductible is generally paid when you make a claim to which it applies. Your premium, on the other hand, is paid according to your policy’s payment schedule.
Is a higher deductible always better?
No. A higher deductible may reduce your premium, but it also means you must pay more toward an applicable claim. It is important to choose an amount you can afford.
Can I change my insurance deductible?
Many insurers allow policyholders to change their deductible, subject to policy terms and approval. Changing it may affect your premium and coverage arrangements.
What happens if my repair cost is lower than my deductible?
If your covered repair cost is lower than your applicable deductible, you generally pay the full repair cost yourself because the loss does not exceed the deductible.
Which is more important: premium or deductible?
Both matter. The premium affects your regular insurance expenses, while the deductible affects how much you may need to pay when making a claim. You should consider both when comparing policies.
Final Thoughts
Understanding insurance premium vs. deductible is an important part of choosing the right insurance policy.
Your premium is the regular amount you pay to maintain coverage, while your deductible is the amount you may have to pay toward an applicable claim.
A lower premium with a high deductible may look attractive, but it could cost you more after an unexpected loss. On the other hand, a higher premium with a lower deductible may provide more predictable claim expenses.
Before purchasing insurance, compare different options, review the policy details, and choose a balance that fits your budget and financial situation.

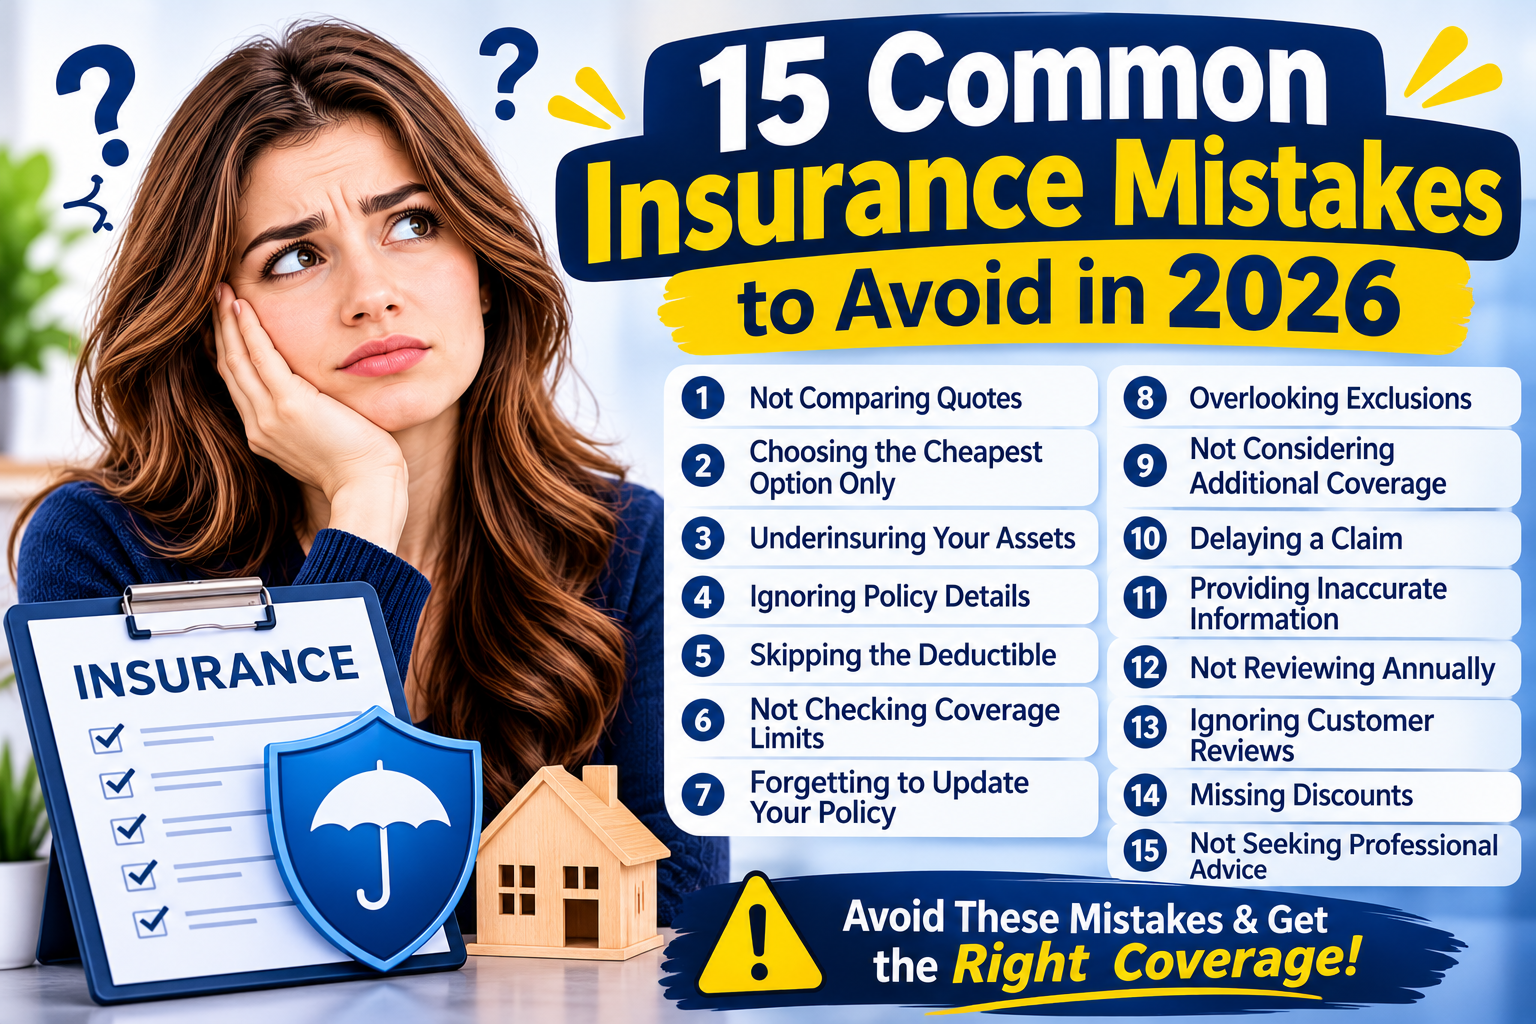
Pingback: 15 Common Insurance Mistakes to Avoid in 2026